
Why Most Loan Requests Get Denied Before They're Read
Here's something most business owners don't know: a loan officer can often tell within the first five minutes whether a request is going anywhere.
Not because we're judging your business. Most of the time, the business is fine. Sometimes it's better than fine. The problem is the request. It was thrown together the week before, half the documents are missing, and it reads like the owner is guessing what the bank wants to hear.
I've spent 30 years on the other side of that desk. Here's what I've learned: most loan requests don't get denied because of a bad business. They get denied because of a preparation gap.
The profitable business that couldn't get to yes
I once sat across from a man who ran an HVAC company. Fifteen years in business. Loyal customers. Steady growth. He wanted financing to buy out a competitor, and on paper he should have been an easy yes.
Then we opened his file. His financials were a mess. His tax returns didn't match his P&L, and when I asked why, he couldn't explain it. He wasn't hiding anything. He just didn't know.
We sent him back to his accountant. Then we sent him back again. By the time his numbers were clean enough to start underwriting, the seller had run out of patience and walked away.
He didn't lose that deal because his business was weak. He lost it because nobody had told him what the bank needed to see, and when.
That's the real tragedy in commercial lending. Good businesses lose good opportunities every day for reasons that have nothing to do with how good the business is.
The three gaps that sink a request
When a request dies early, it's almost always one of these three things.
It was thrown together at the last minute. The owner finds a building, a business to buy, or a piece of equipment, and then starts pulling paperwork together. Bankers can tell. A rushed request tells us you might run the loan the same way.
Documents are missing or don't match. Tax returns that don't tie to the P&L. A personal financial statement from two years ago. Interim numbers that stop in March. Every gap means another round of back-and-forth, and every round costs you time you may not have.
It's written to guess, not to explain. Some owners tell the bank what they think it wants to hear: big projections, round numbers, no explanation of the bad year. That's backwards. A banker trusts an owner who understands their own numbers, dips included.
None of these are about whether your business is good. All three are fixable before you ever walk in the door.
The five things every banker is really looking at
No matter which bank you go to or which loan officer you sit with, every decision comes back to the same framework bankers have used for decades. We call it the 5 C's of Credit.
Character: Can we trust you? Your track record, your history, how you handle hard questions.
Capacity: Can the business actually repay this, in an average year and a bad one?
Capital: How much of your own money is in the game?
Collateral: If things go wrong, what's the bank's fallback?
Conditions: What's happening in your industry, the economy, and with how you'll use the money?
I'll be breaking down each one in this series, one post at a time. If you understand them going in, you're not just hoping for approval. You're building a case for it.
Start before you need the money
The owners who get approved aren't always the ones with the best businesses. They're the ones who show up prepared. They know their numbers, they can explain the dips, and they hand over a clean package the first time.
The best time to get ready for a loan is before you need one. Get your financials in order now. Make sure your tax returns and your P&L tell the same story. Know how you'd answer the hard questions.
Do that, and you walk into the bank as the easy yes instead of the file that gets sent back twice.
Want the full playbook? My ebook, Approved: How Bankers Actually Decide, walks through all five C's, what to put in your loan package, the red flags bankers watch for, and how to choose between SBA and conventional loans. It's $7.99 at howbankersdecide.com.
Next in the series: Character, the trust factor, and why a banker is sizing you up before they look at a single number.
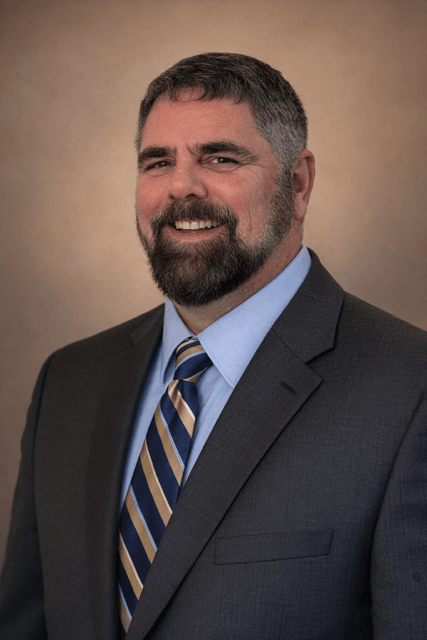
HEY, I’M KEVIN…
I spent over 30 years as a commercial banking relationship manager, sitting on the other side of the desk for thousands of business loan decisions. I wrote "APPROVED: HOW BANKERS ACTUALLY DECIDE" to share what actually happens in loan committee -- the details that quietly move a deal from "maybe" to "yes". On this blog, I break down the real reasons loans get approved or denied, so you know what to expect before you ever apply.

JOIN MY MAILING LIST

Created with © systeme.io